
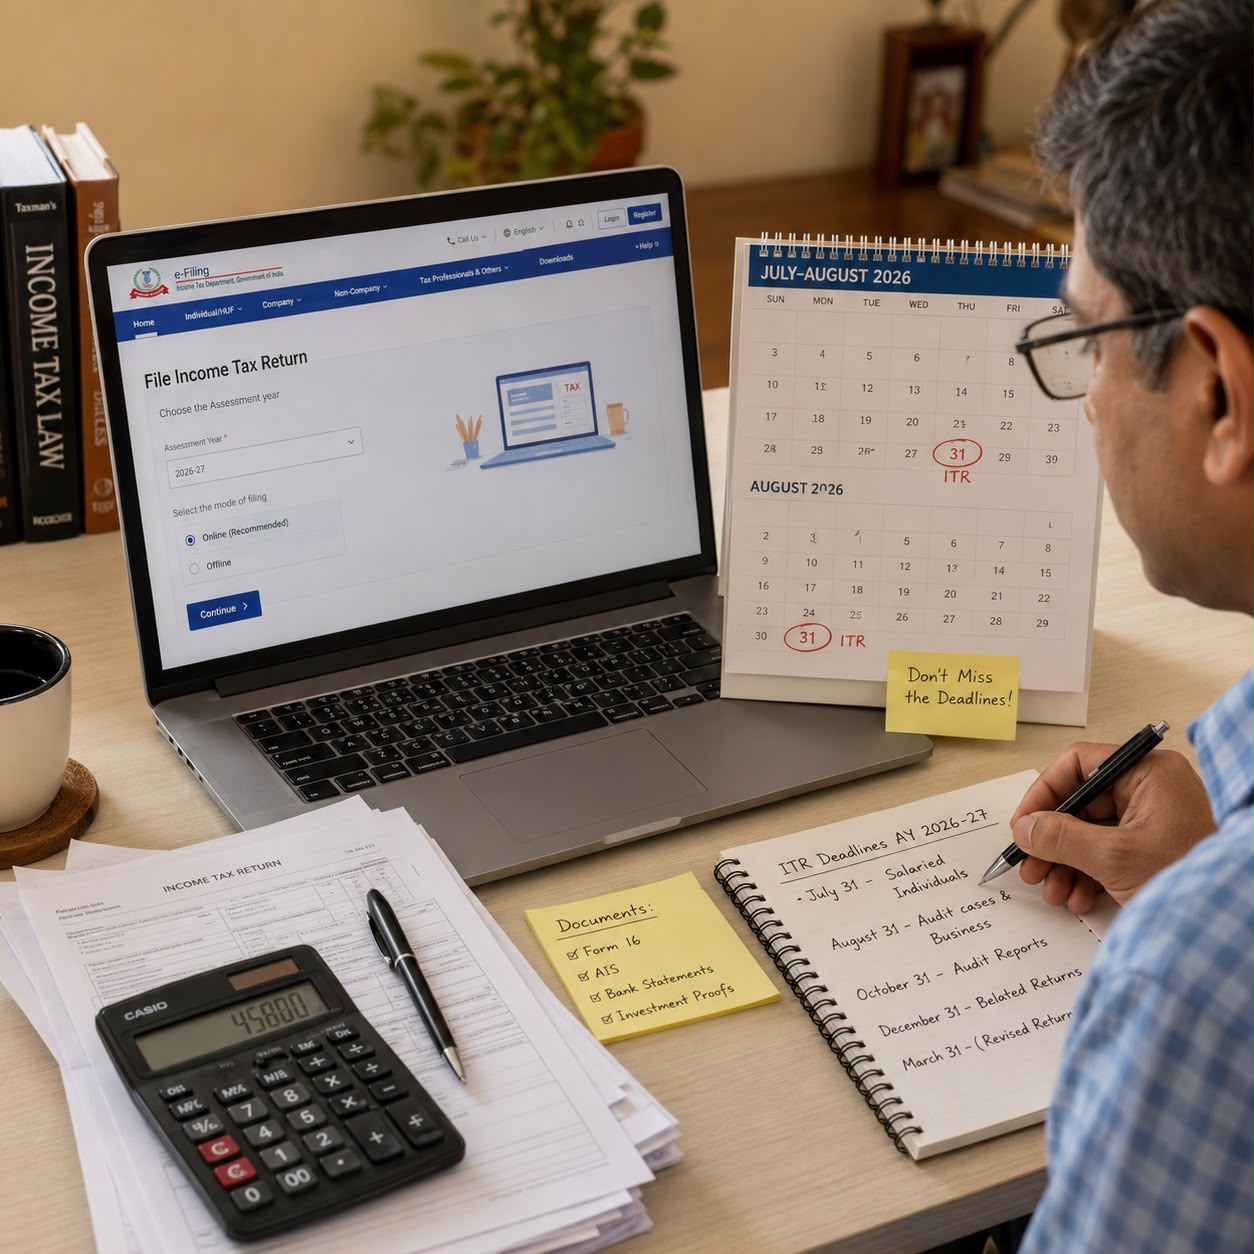
July 31 and August 31 are the most important deadlines for taxpayers; delayed filing can attract penalties.
News Story:
New Delhi, June 17, 2026: Taxpayers filing Income Tax Returns (ITR) for Assessment Year (AY) 2026-27 should keep a close watch on key deadlines to avoid penalties, interest charges, and delays in processing refunds. Tax experts emphasize that filing returns on time not only ensures compliance but also offers several financial benefits.
For salaried individuals and most regular taxpayers, July 31, 2026, remains the most important deadline for filing ITR. Missing this date could lead to late filing fees and other consequences under the Income Tax Act.
Small business owners who are not subject to tax audit have an extended deadline of August 31, 2026, to file their returns.
Meanwhile, businesses and professionals whose accounts require an audit must submit their returns by October 31, 2026.
Taxpayers who miss the original filing deadlines still have an opportunity to submit a belated return until December 31, 2026. However, delayed filing may result in penalties and loss of certain tax benefits.
If any mistakes are discovered after filing, taxpayers can revise their returns until March 31, 2027, allowing them to correct errors and update information.
For those who fail to file even a belated return, the Income Tax Department provides the option of filing an updated return, with the final deadline extending up to March 31, 2031, subject to applicable conditions and additional taxes.
Experts advise taxpayers not to wait until the last minute, as timely filing helps ensure faster refund processing, easier loan approvals, and smoother financial record-keeping.










