Atal Pension Yojana and the National Pension System offer different paths to retirement security. Here’s how they compare in terms of returns, risk, flexibility, and eligibility.
Key Highlights
- APY offers guaranteed monthly pension benefits.
- NPS provides market-linked retirement returns.
- APY is aimed mainly at the unorganised sector.
- NPS is open to Indian citizens and NRIs up to 70 years.
- APY carries lower risk, while NPS offers higher return potential.
- Investors can combine both schemes for balanced retirement planning.
Updated News Article
New Delhi, June 16: Choosing the right retirement plan can be confusing, especially when two popular options—Atal Pension Yojana (APY) and the National Pension System (NPS)—offer very different benefits. While APY provides a guaranteed monthly pension backed by the government, NPS offers market-linked returns with the potential for higher wealth creation over the long term.
Understanding the differences between these two schemes can help investors make informed retirement decisions based on their financial goals and risk appetite.
What Is Atal Pension Yojana (APY)?
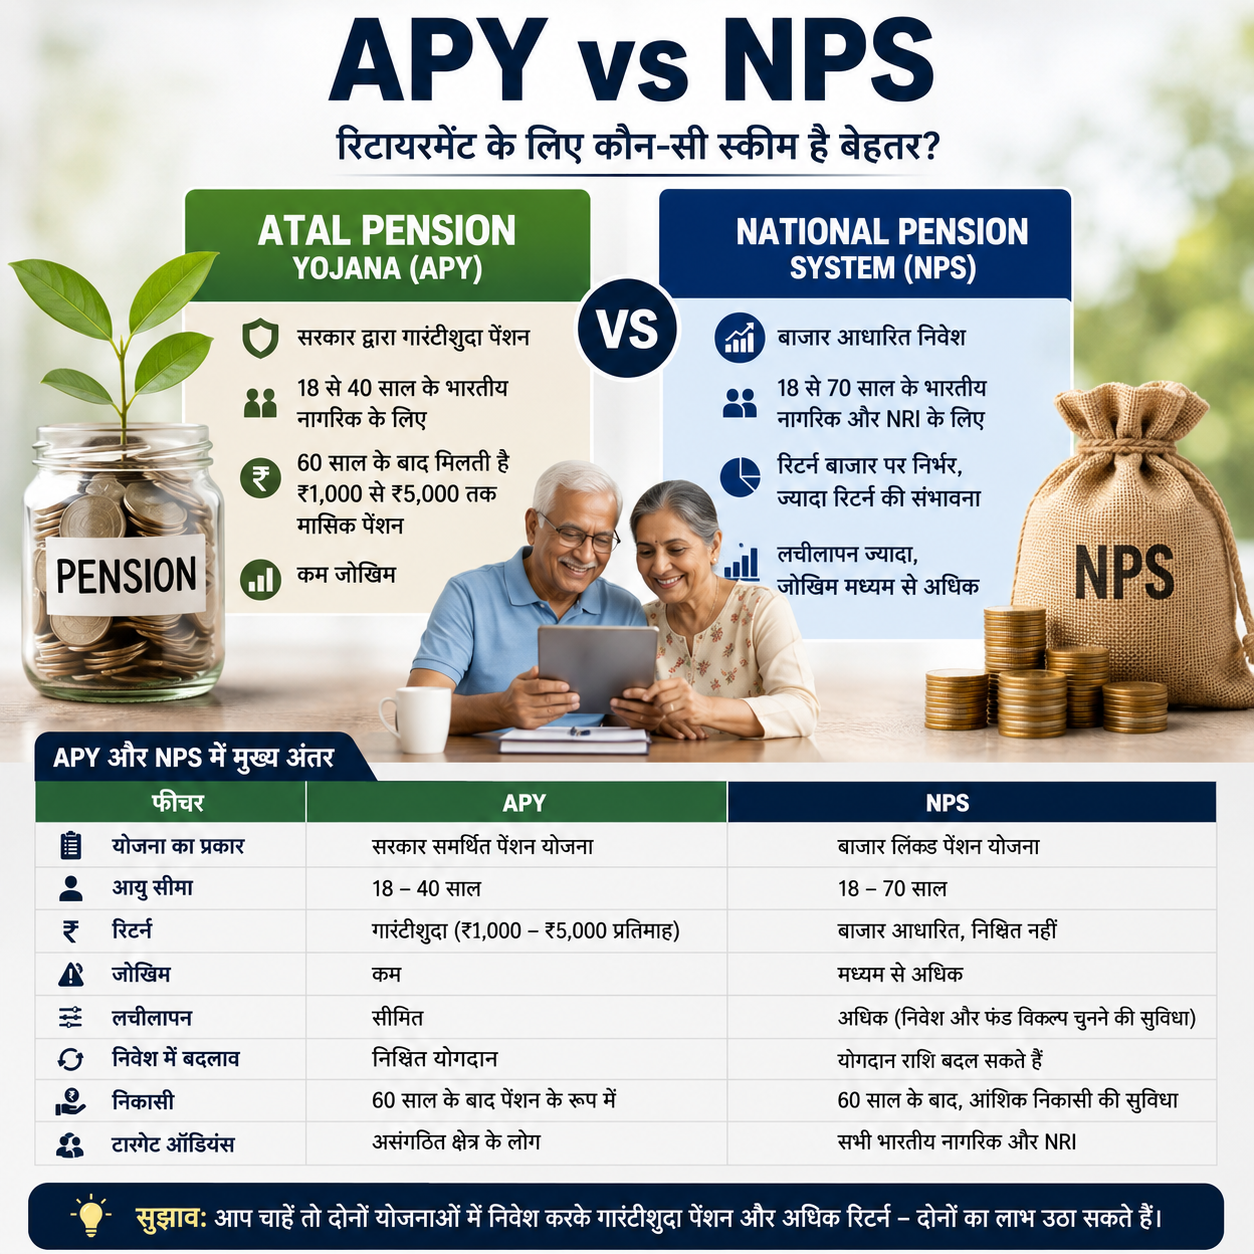
Atal Pension Yojana is a government-backed social security scheme designed primarily for workers in the unorganised sector.
- Individuals aged 18 to 40 years can enroll.
- Subscribers receive a guaranteed monthly pension ranging from ₹1,000 to ₹5,000 after the age of 60.
- The pension amount depends on the contribution made and the age at which the subscriber joins.
- Returns are fixed and unaffected by market fluctuations.
What Is National Pension System (NPS)?
The National Pension System is a market-linked retirement savings scheme regulated by the Pension Fund Regulatory and Development Authority (PFRDA).
- Indian citizens and NRIs aged 18 to 70 years can invest.
- Funds are allocated across equity, corporate bonds, and government securities.
- Returns are not guaranteed and depend on market performance.
- Investors can modify contribution amounts and choose asset allocation preferences.
APY vs NPS: Key Differences
| Feature | APY | NPS |
|---|---|---|
| Nature of Scheme | Government-backed pension | Market-linked retirement plan |
| Age Eligibility | 18–40 years | 18–70 years |
| Returns | Guaranteed pension | Market-dependent |
| Risk Level | Low | Moderate to High |
| Flexibility | Limited | High |
| Target Audience | Unorganised sector workers | All Indian citizens and NRIs |
| Pension Benefit | Fixed monthly pension | Corpus-based retirement income |
Which Scheme Should You Choose?
If you prefer stability, lower risk, and a fixed pension after retirement, Atal Pension Yojana can be an ideal choice.
However, if you are comfortable with market risks and aim to build a larger retirement corpus with potentially higher returns, National Pension System may be more suitable.
Financial experts also suggest that investors can consider investing in both schemes to enjoy the dual benefits of guaranteed pension income and market-linked wealth creation.