Coking Coal Costs Lift Prices
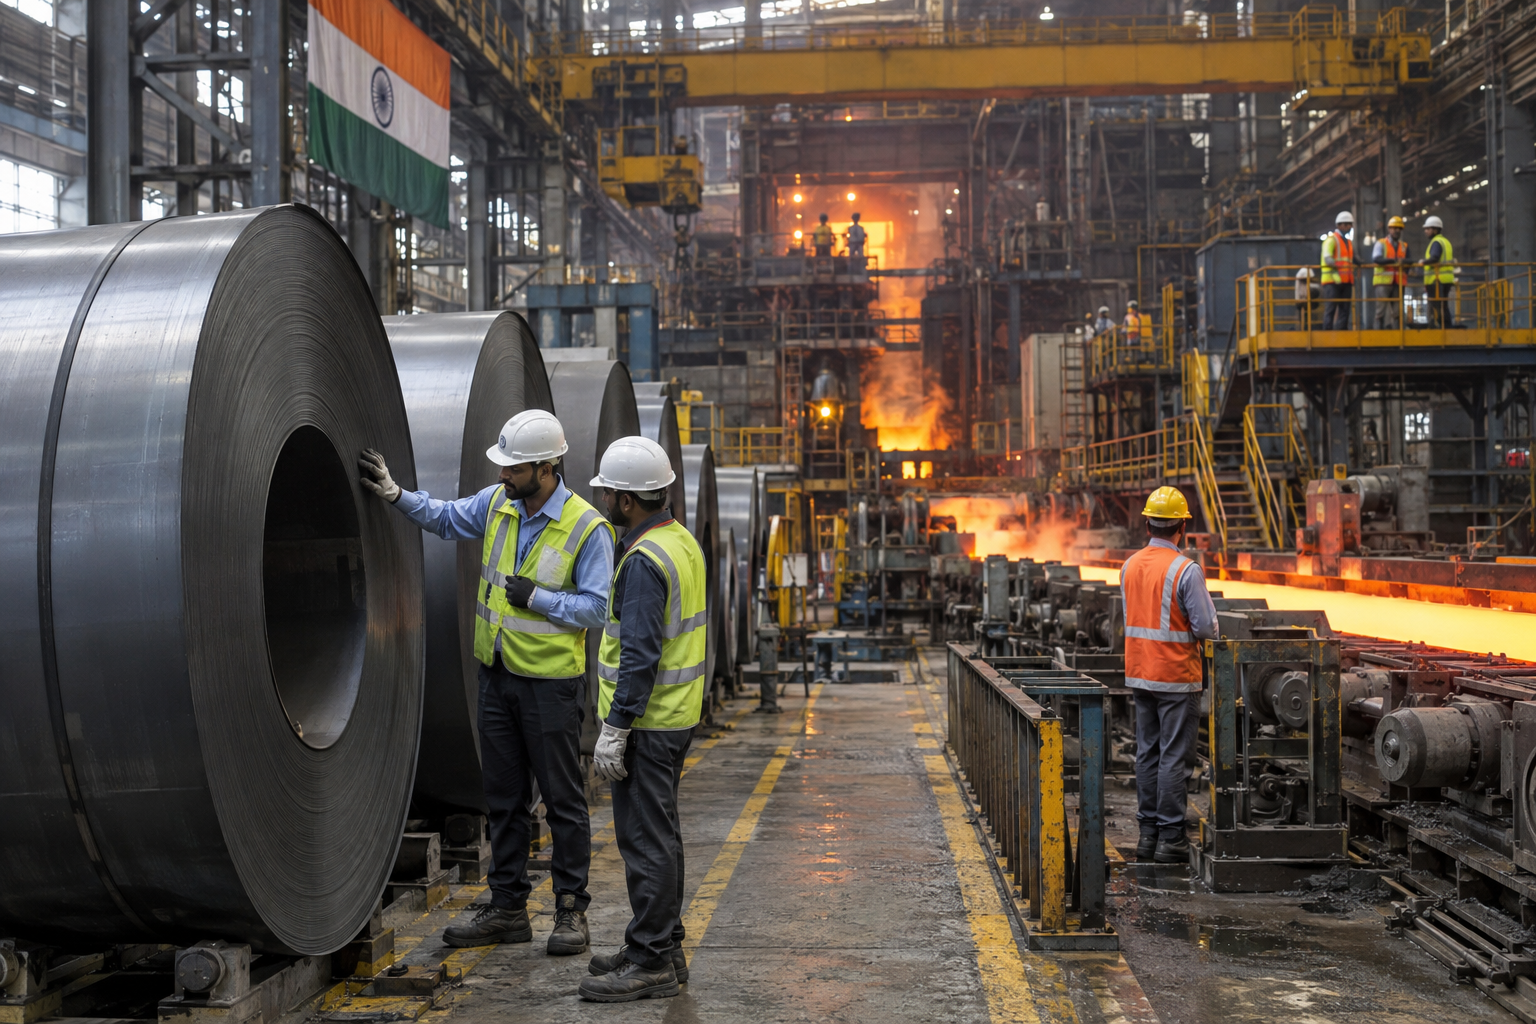
Indian steel prices are expected to rise further in the coming weeks as a post-monsoon recovery in infrastructure and automotive demand coincides with higher coking coal costs, tighter market availability and relatively lean distributor inventories.
The expected increase follows a sharp recovery in domestic steel prices during August and early September. According to commodities consultancy BigMint, hot-rolled coil (HRC) prices have increased by around ₹4,000 per tonne since August, reaching a four-year high.
The rise comes after a relatively modest price correction earlier in the year. Government data showed that Indian steel mills had reduced prices of products such as HRC by about ₹280 per tonne between June and July.
Market participants now expect the upward trend to continue as steel consumption typically gains momentum after the monsoon season. Infrastructure projects, construction activity and automobile production are expected to support demand, while festive-season restocking could provide an additional boost.
Vedant Goel, director at Enlight Metals, expects steel prices to increase by around ₹3,500 per tonne in the coming weeks, highlighting the strength of the current market conditions.
A major factor behind the expected price increase is the rise in coking coal costs. Coking coal is a key raw material in conventional steelmaking and accounts for a significant portion of production costs. As the cost of the input rises, steel producers face pressure to raise finished-steel prices in order to protect margins.
The pricing environment has also been supported by temporary supply constraints. Planned maintenance shutdowns at major steel mills have reduced available production, while tighter spot availability and lower distributor inventories have strengthened the market.
Steelmakers could therefore find themselves in a more favourable pricing environment after facing margin pressure from higher input costs. Passing part of the increased coking coal cost on to customers would allow producers to recover some of the margin lost during the period of rising raw-material expenses.
However, the ability of Indian mills to push prices substantially higher could be constrained by imports.
Steel imports, particularly from China, have increased despite measures introduced by India to protect domestic producers. The government imposed a safeguard duty on certain steel imports last year following concerns about a surge in overseas supplies. India also launched an anti-dumping investigation in June into HRC imports from China, Japan and Russia.
Higher imports could give buyers more alternatives and limit the pricing power of domestic mills. This is likely to be an important factor for the market as producers attempt to pass higher raw-material costs on to downstream customers.
For infrastructure and construction companies, sustained steel-price increases could raise project costs at a time when demand is already strengthening. Automobile manufacturers and component suppliers could also face higher material expenses because steel remains an important input across the automotive value chain.
The impact will depend partly on how much of the increase producers are able to pass through and how quickly downstream companies adjust their procurement strategies.
The current market also reflects a broader improvement in domestic steel demand. As the monsoon season ends, construction activity generally picks up, while infrastructure spending and project execution can increase steel consumption. Festive demand and restocking by distributors could further support prices in the near term.
At the same time, the sustainability of the rally will depend on the balance between domestic demand, production availability, input costs and imports.
For Indian steelmakers, the immediate environment appears supportive: demand is recovering, inventories are relatively lean and raw-material costs are rising. But the presence of imported steel means that price increases are unlikely to be unlimited.
With India remaining the world’s second-largest crude steel producer after China, developments in domestic steel prices will have implications well beyond the steel industry, particularly for infrastructure, construction, engineering and automotive companies.
The coming weeks will therefore be closely watched by both producers and steel-consuming industries. If post-monsoon demand remains firm while coking coal costs stay elevated, steel prices could extend their recent gains, potentially improving mill margins but increasing input-cost pressure across several major sectors.